
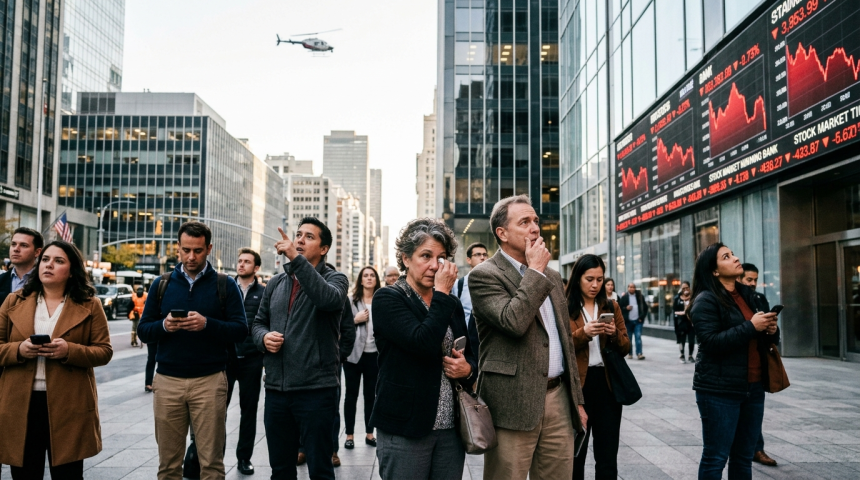
A sharp stock market sell-off drove major indexes lower Thursday, renewing concern among Americans whose retirement savings depend on market performance.
The decline prompted financial experts to address worried 401(k) investors. Their attention reflects a familiar challenge: retirement accounts can show sudden losses, even when workers have decades before leaving the workforce.
Why Market Losses Reach Retirement Accounts
Many 401(k) plans invest in stock funds, bond funds, or target-date funds. Their values move with the assets they hold, so a broad sell-off can quickly reduce account balances.
That paper loss can feel immediate, but its long-term effect depends on several factors. These include an investor’s age, asset mix, contribution rate, and expected retirement date.
Workers early in their careers usually have more time to recover from market declines. Those near retirement may face greater pressure because they could need to withdraw money sooner.
Thursday’s drop also shows why daily market moves receive so much attention. A 401(k) balance may represent years of payroll contributions, employer matches, and investment gains. Watching that number fall is nobody’s preferred lunch-break activity.
Short-Term Fear Meets Long-Term Planning
Financial experts often warn that emotional decisions during a sell-off can lock in losses. Selling after prices have dropped may also leave investors on the sidelines during a later recovery.
Still, holding every investment without review is not a universal answer. A portfolio designed for a 30-year-old may not fit someone preparing to retire next year.
Investors assessing their accounts can focus on a few practical questions:
- Does the current mix match the planned retirement date?
- Is the account spread across different types of investments?
- Would another decline force withdrawals at a bad time?
- Have personal goals changed since the last portfolio review?
These questions shift attention from the market’s latest swing to matters an investor can control. Contribution levels, fees, diversification, and risk exposure can shape results over many years.
Different Workers Face Different Risks
Younger employees may view lower stock prices as an opportunity because regular contributions can purchase more shares. This approach does not prevent losses, but it can reduce the impact of buying at one price.
Older workers have a different concern, known as withdrawal timing risk. Taking money from a falling portfolio can leave fewer assets available for a recovery.
Near-retirees may therefore examine whether they hold enough lower-volatility assets or cash for upcoming expenses. Any change should fit a written plan rather than Thursday’s headlines alone.
People who are unsure about their risk level may seek advice from a qualified financial professional. They should also review costs and potential conflicts before accepting recommendations.
What Investors Should Watch Next
One difficult trading session does not establish a lasting market trend. Further movement may depend on corporate earnings, interest-rate expectations, economic reports, and investor confidence.
For retirement savers, the larger lesson is less dramatic than the market ticker. A 401(k) is usually built for years or decades, while sell-offs can unfold within hours.
Thursday’s decline offers a timely reason to review risk, but not necessarily to rewrite a retirement plan overnight. Investors should watch whether losses persist, check that their holdings match their timelines, and avoid letting panic make expensive decisions.