
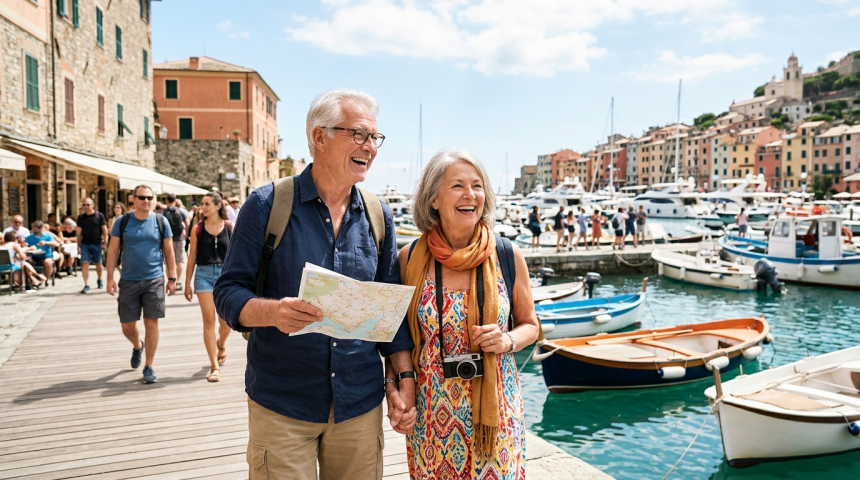
A growing retirement philosophy is urging older people to spend their savings while they can, rather than preserve a large estate for later.
The phenomenon centers on retirees using their money to enjoy life fully. Travel, hobbies, family gatherings and personal goals can take priority over leaving the largest possible inheritance.
Supporters see the approach as a practical response to a simple fact: money may offer more value when health and independence remain strong. Critics warn that spending too freely can create serious problems during a long retirement.
Why Some Retirees Are Spending More
Traditional retirement advice often emphasizes careful withdrawals and preserving capital. That model offers security, but it can also leave cautious savers reluctant to use money set aside for their later years.
The newer approach turns that logic around. Its central idea is not reckless consumption. Instead, retirees plan to use more of their wealth on meaningful experiences during their lifetime.
The phenomenon sees retirees spend all their money on “enjoying life to the full.”
Timing is central to the argument. Some experiences become harder with age, even if the money remains available. A demanding trip may be manageable at 65 but unrealistic at 85.
Spending can also benefit relatives before an estate is settled. Retirees may pay for shared holidays, education or housing support while they can see how the money helps.
The Risk of Living Longer
The obvious problem is that nobody knows the length or cost of retirement. A person who spends rapidly could face decades of future expenses.
Housing, care and medical costs may rise as retirees age. Inflation can also weaken purchasing power, while market losses can reduce investment income at an awkward time.
Key questions for retirees include:
- Whether reliable income covers essential monthly expenses
- How much cash is reserved for emergencies
- Whether future care costs have been considered
- How spending plans would survive a market downturn
The philosophy may therefore suit wealthier households better than people with limited savings. Those relying mainly on fixed retirement income have less space for an expensive last lap.
Inheritance Expectations May Change
Spending down wealth can reshape family finances. Adult children may receive smaller inheritances than expected, especially when parents prioritize travel and leisure.
That choice can cause tension if families have made assumptions about property, investments or other assets. Clear discussions can reduce surprises and help distinguish a retirement plan from impulsive spending.
There is also a middle course. Retirees can reserve money for essential needs, set aside planned gifts and create a separate budget for experiences. This preserves freedom without treating the savings account like a countdown clock.
Planning Still Matters
The trend challenges the idea that retirement success is measured by the amount left behind. It instead treats savings as a tool for supporting a satisfying life.
Yet the safest version depends on disciplined planning. Retirees must weigh current enjoyment against longevity, inflation and care needs. The goal is to avoid both extremes: needless deprivation and premature financial exhaustion.
As more people reconsider inheritance and later-life goals, advisers and families will need to discuss what retirement money is actually for. The answer may include richer experiences, but it should also leave enough for an uncertain tomorrow.