
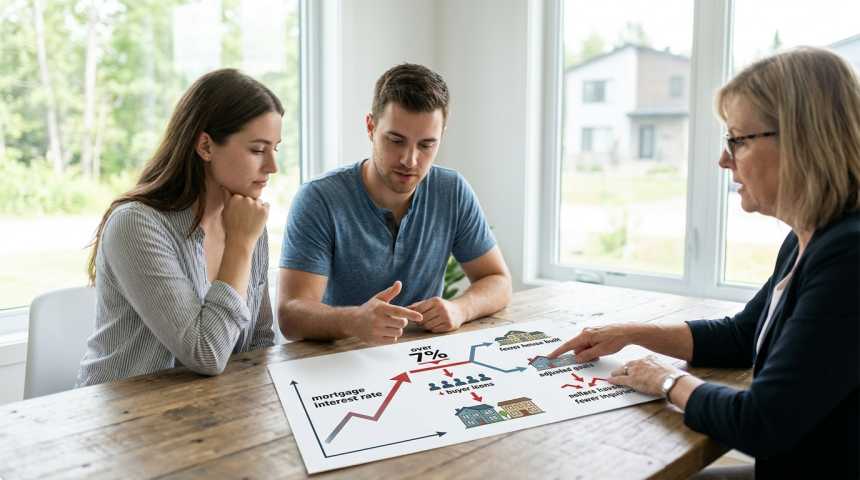
Mortgage rates above 7% may no longer be a temporary shock, forcing homebuyers, sellers, and lenders to rethink the housing market.
The central assessment is blunt: higher borrowing costs are becoming normal rather than exceptional. That shift matters because mortgage rates shape monthly payments, purchasing power, home prices, and construction activity.
“Mortgage rates above 7% are the new normal.”
No forecast period or supporting data accompanies that assessment. Still, treating 7% as a lasting benchmark offers a useful test for household budgets. Buyers can plan around current costs instead of waiting for a rapid return to cheaper loans.
Higher Rates Change Buyer Budgets
A mortgage rate does not merely affect the interest line on a loan document. It can determine whether a household qualifies for financing at all.
As rates rise, monthly payments increase for the same loan amount. Buyers must then choose among several imperfect options:
- Purchase a less expensive home.
- Make a larger down payment.
- Accept a higher monthly payment.
- Delay the purchase and keep renting.
The effects can be especially sharp for first-time buyers. They often have less home equity, smaller cash reserves, and fewer ways to reduce the amount borrowed.
Higher rates can also create a misleading focus on the headline number. Taxes, insurance, maintenance, fees, and mortgage terms remain important. A lower advertised rate may carry upfront costs that reduce its value.
Sellers Face a Lock-In Problem
Persistently expensive mortgages can limit the number of homes offered for sale. Owners with cheaper existing loans may hesitate to move because a new mortgage could cost far more each month.
That reluctance may keep housing supply tight even as demand weakens. The result is an awkward market: fewer buyers can afford homes, but fewer owners are willing to sell them. Housing, as usual, refuses to make the math convenient.
Sellers may need to adjust through price cuts, repair credits, or help with closing costs. Builders could also use temporary rate reductions or other incentives to attract buyers.
“Normal” Does Not Mean Permanent
Calling rates above 7% normal is an expectation, not a guarantee. Mortgage pricing can change with inflation, economic growth, bond markets, central bank policy, and lenders’ views of risk.
Rates could fall if inflation cools and financial conditions ease. They could remain elevated if price pressures persist. They could also rise further after economic or market shocks.
That uncertainty makes precise predictions risky. A household should not assume that refinancing will rescue an unaffordable purchase later. Refinancing depends on future rates, home values, credit quality, fees, and lender approval.
A New Planning Standard
The practical response is not panic. It is stricter budgeting. Buyers can compare offers from several lenders, review different loan structures, and calculate payments under less favorable conditions.
Consumers should also test whether they could manage taxes, insurance increases, repairs, and income disruptions. Approval for a loan does not prove that the payment fits comfortably within a household budget.
If rates above 7% persist, the housing market may adjust slowly through wages, prices, construction, and buyer expectations. That process may take longer than hopeful shoppers or eager sellers would prefer.
The main takeaway is simple: planning for high rates is safer than betting on quick relief. Future inflation readings, lending conditions, home inventory, and monthly payment trends will show whether the 7% era is durable or merely an unusually long chapter.