
Thursday’s mortgage-rate report puts adjustable-rate loans in focus as homebuyers compare financing options during their housing search.
The report is intended to help shoppers choose a mortgage that fits their needs. It highlights average rates for adjustable-rate mortgages, often called ARMs. No specific rate figures were provided in the initial notice.
Why Adjustable Rates Matter
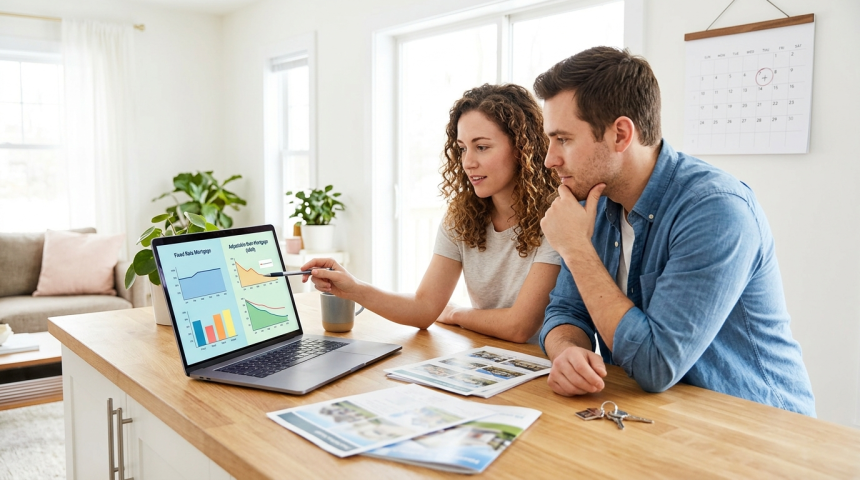
An adjustable-rate mortgage usually starts with an interest rate that remains fixed for a set period. After that period, the rate may rise or fall at scheduled intervals.
This structure can offer a lower starting rate than a fixed-rate mortgage. However, future payments may become less predictable once adjustments begin.
Homebuyers can review average adjustable mortgage rates “so you can pick the best home loan for your needs as you house shop.”
The best choice depends on more than the advertised rate. Buyers must consider how long they expect to own the home, their monthly budget, and their ability to absorb higher payments.
What Buyers Should Compare
Average mortgage rates give shoppers a useful benchmark. Yet an individual offer may differ based on credit history, income, debt, down payment, property type, and lender fees.
Before selecting an ARM, borrowers should review several terms:
- The initial rate and how long it stays fixed
- The index used for later adjustments
- The lender’s added margin
- Limits on each increase and lifetime changes
- Closing costs, fees, and possible prepayment rules
An ARM labeled 5/1, for example, generally has a fixed rate for five years and then adjusts once each year. Other products use different fixed periods and adjustment schedules.
Rate caps can limit payment shocks, but they do not remove the risk. A loan may still become much more expensive over time if market rates climb.
Fixed Rates Offer a Different Trade-Off
Fixed-rate mortgages keep the same interest rate throughout the loan term. That provides stable principal and interest payments, which can make household budgeting easier.
ARMs may appeal to buyers who plan to sell or refinance before the first adjustment. They can also suit borrowers with enough financial room to manage possible increases.
That strategy carries uncertainty. Refinancing depends on future rates, home values, credit conditions, and lender approval. Selling may also take longer than expected.
A low opening rate should therefore be treated as one part of the decision, not the whole answer. The annual percentage rate can offer a broader view because it reflects certain borrowing costs.
Thursday’s Figures Need Context
Mortgage averages can change as bond markets, inflation expectations, and economic data shift. A weekly or daily reading is a snapshot rather than a guaranteed offer.
Borrowers may benefit from requesting written estimates from several lenders on the same day. Comparing identical loan amounts and terms can reveal differences hidden by headline rates.
Homebuyers should also ask lenders to calculate the highest possible payment under the loan’s caps. That stress test can show whether an ARM remains affordable after its introductory period ends.
Thursday’s report can help shoppers track borrowing costs, but careful comparison remains essential. The next details to watch are the published averages, adjustment terms, and total fees. For buyers, the smartest loan is not always the one with the lowest first payment. It is the one that still fits if plans, rates, or budgets change.