
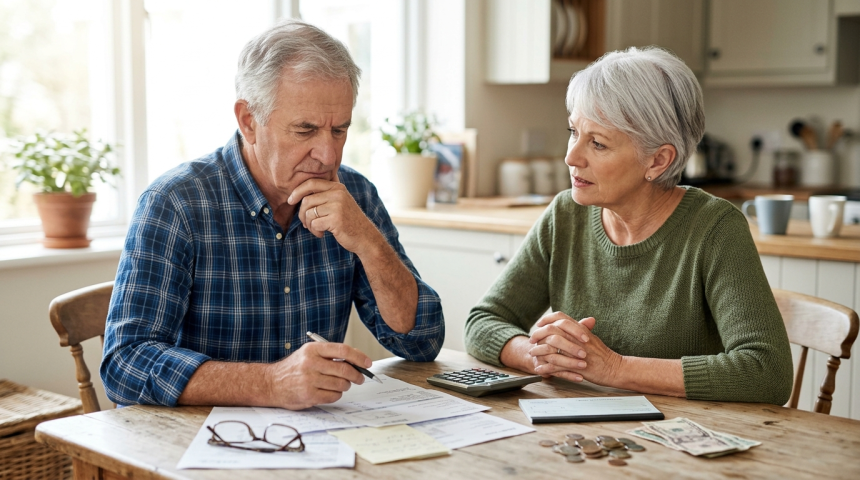
Retirees who rush to clear every debt balance may weaken their finances just as regular paychecks end. Paying off loans can reduce monthly costs and stress. Yet using too much cash may leave households short of funds for medical bills, repairs, taxes, and other urgent needs.
The concern is timely for people nearing retirement and deciding how to use savings. The right choice depends on interest rates, cash reserves, taxes, investment risk, and expected income. It is not simply a choice between debt and no debt.
Liquidity Can Matter More Than a Zero Balance
Debt repayment offers a clear benefit. Each paid balance removes future interest and lowers required monthly spending. That can make a fixed retirement income easier to manage.
However, a large final payment may drain an emergency fund. Once cash is used to repay a lender, getting it back may require a new loan. Approval could be harder after employment income stops.
“Rushing to wipe out every debt balance before retirement could come with some surprising tradeoffs.”
Those tradeoffs are often most serious during the first years of retirement. A major home repair, family emergency, or health expense can arrive without warning. Selling investments during a market decline may then lock in losses.
Keeping accessible savings can provide a buffer. It may also help retirees avoid placing emergency expenses on high-rate credit cards.
Not All Debt Carries Equal Risk
A high-interest credit card balance presents a different problem from a low-rate, fixed mortgage. Credit card interest can quickly increase costs, while a fixed home loan may offer predictable payments.
Borrowers can sort debts by several practical measures:
- The interest rate and whether it can change
- The size and timing of required payments
- Any tax cost tied to withdrawals used for repayment
- The amount of emergency cash left afterward
- The borrower’s comfort with carrying debt
Paying high-rate debt first can deliver a strong, certain return through avoided interest. Lower-rate debt may justify a slower approach if the household needs cash flexibility.
Taxes Can Change the Calculation
The source of repayment money matters. Taking a large sum from a tax-deferred retirement account may increase taxable income for that year. It could also affect health insurance costs or other income-based expenses.
Investment returns are uncertain, so keeping money invested is not always better than repaying debt. Still, withdrawing assets without reviewing the tax effect can make a payoff more expensive than expected.
Mortgage decisions also require care. Clearing a home loan lowers housing costs, but it can concentrate more wealth in the property. Home equity may be less accessible than money held in savings.
A Plan Should Reflect Retirement Income
Households with pensions, Social Security benefits, or other steady income may manage predictable debt payments more easily. Those relying heavily on market investments may place greater value on lower monthly obligations.
Personal preference also counts. Some retirees gain peace of mind from owning their homes outright. Others prefer to keep cash available, even if that means continuing manageable payments.
A measured plan may combine both goals. A household could repay costly balances, preserve an emergency reserve, and make extra payments on lower-rate loans over time. Reviewing withdrawal taxes before transferring money can prevent an avoidable surprise.
Entering retirement debt-free can be valuable, but it should not come at the cost of financial resilience. The central issue is whether repayment improves the full retirement plan. Future retirees should watch interest rates, tax effects, cash needs, and income stability before making a final payoff.